You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that’s left you reluctant to buy a home, it’s important to remember that’s not necessarily the number you’d get.
It’s a common misconception that the rate you see in the headlines is the same one you’d get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about.
What Determines Your Real Rate?
Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that.
Only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at:
- Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate.
- Your debt-to-income ratio (DTI): This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be.
- The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage.
- The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs.
Even after you find a home you love, other things can have an impact too. For example:
- A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy.
- Seller concessions: Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate.
There’s a lot that can ultimately have an impact on your actual rate.
Your First Step? Getting Pre-Approved.
If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be.
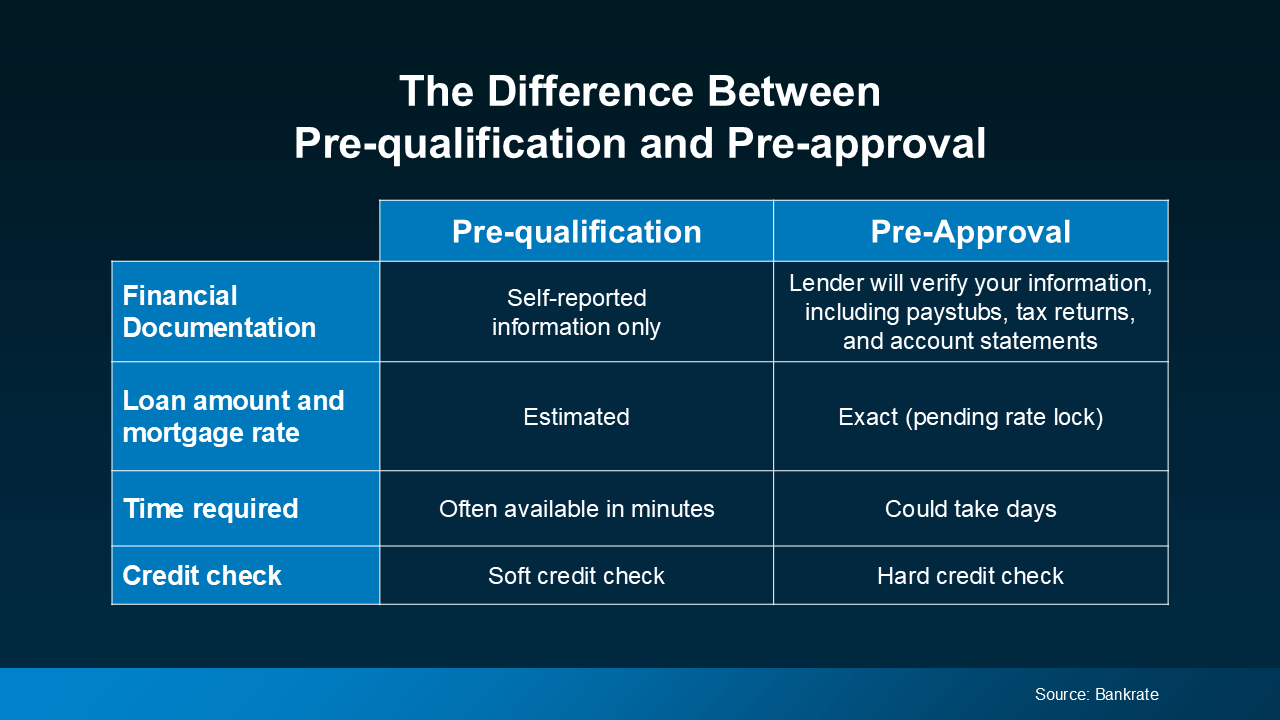
Your lender may recommend a pre-qualification and pre-approval:
- Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information.
- On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information.
Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:
How To Get Ready for the Conversation
Ask your lender what documents you’ll need to gather for that conversation. And keep these questions in your pocket too. They’re good things to go over when you talk:
- What will I gain or lose by waiting to buy a home for 3, 6, or 12 months?
- Will I get any tax advantages by buying a home – and what are they?
- What’s the benefit of buying a home and starting to build equity now versus waiting? And how does that impact my finances in the long run?
- How will rate changes in either direction affect me?
Once you find out your rate, you’ll know your options and can make an informed decision.
Headlines and social media make today’s rates sound high. The only way to know what your rate could be is to talk to a trusted lender.
Need a recommendation for a lender? Get in touch.
Cover Photo by Jakub Żerdzicki on Unsplash